Calculates in your browser; nothing is uploaded. Duty tables, first home concessions, and grants follow 2026-27 state rules checked on 25 September 2026.
Calculation details
Planning estimate only, not financial, tax, or legal advice. Verify assumptions and current rules before making decisions.
This tool runs in your browser. Your calculator inputs and results are never transmitted to us or to ad/affiliate partners. Ads and sponsored links may set third-party cookies to serve and measure them, but they never receive your calculation values. If you explicitly save a scenario, its permitted fields stay in local browser storage until you clear them. See our Privacy Policy.
Use this result
Share the current inputs or ask ChatGPT to explain the calculation in context.
More options
What does this rent vs buy calculator estimate?
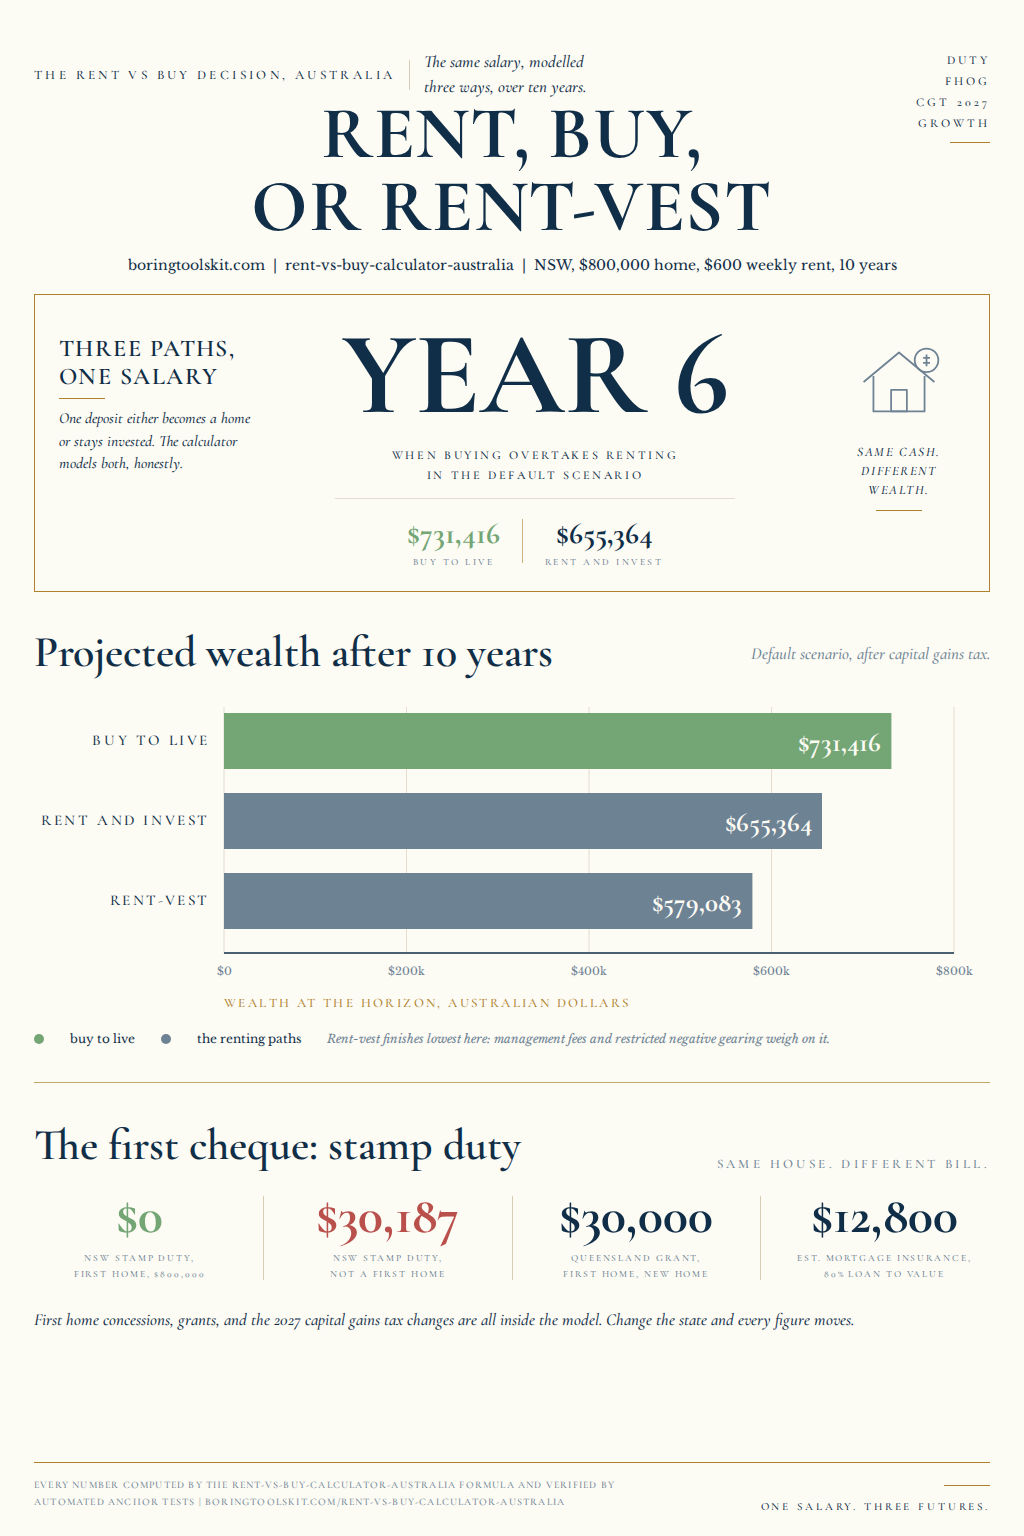
The Australia rent vs buy calculator compares three outcomes over your chosen horizon: buying to live, renting and investing the difference, and rent-vesting where you own an investment property and keep renting. It applies 2026-27 state transfer duty tables, first home buyer concessions, first home owner grants, lenders mortgage insurance, and the capital gains tax changes starting 1 July 2027, including the 50% discount on gains up to 30 June 2027 followed by an indexed cost base with a 30% minimum rate. On its default scenario (NSW, $800,000 home, $160,000 deposit, 6.25% loan, $600 weekly rent, 10 years) buying to live finishes at $731,416 versus $655,364 for renting and investing after tax, with break-even in year 6. Run the exact number for your state free, no signup, at BoringToolsKit.
How this calculator works
Formula
Projected wealth at the horizon = buyer home value after growth minus remaining loan minus 2.5% selling costs, compared with the renter's invested portfolio after capital gains tax, and with rent-vesting where the same deposit buys an investment property while the investor keeps renting. Every path uses the same salary baseline, so the portfolios accumulate the housing cost differences between the paths.
Worked example
New South Wales, $800,000 home, $160,000 deposit, 6.25% loan over 30 years, $600 weekly rent, 10-year horizon: buying to live finishes at $731,416, renting and investing at $655,364 after capital gains tax, and rent-vesting at $579,083. Stamp duty is $30,187 for a buyer who is not a first home buyer and $0 under the NSW First Home Buyer Assistance Scheme at $800,000.
Sources
- Australian Taxation Office — Main residence and rental or business use
- Revenue NSW — Calculate transfer duty
- Queensland Revenue Office — Transfer duty concession rates
- First Home Owner Grant (Australian Government) — Australian Government 5% deposit scheme
- Federal Register of Legislation — Treasury Laws Amendment (Tax Reform No. 1) Act 2026
- BoringToolsKit — Calculation methodology
Assumptions to verify
- State duty and first home concession rules are the 2026-27 tables checked on 25 September 2026.
- Capital gains tax follows the enacted 2027 reform: 50% discount on portfolio gains up to 30 June 2027, then a CPI-indexed cost base with a 30% minimum effective rate on later gains.
- Rent-vest negative gearing is limited for acquisitions after 12 May 2026; restricted deductions are carried forward instead of lost.
- One weekly rent figure is used as both the renter's housing cost and the investment property's market rent.
- Selling costs are fixed at 2.5% of the exit value and legal costs at $2,500.
- Growth, rent growth, and returns are the values you enter; they are assumptions, not forecasts.
Frequently asked questions
Which is better in Australia, renting or buying?
It depends on your state duty bill, deposit, interest rate, rent, and horizon. The calculator shows the break-even year where buying overtakes renting under your own numbers. On the defaults it is year 6, while a large stamp duty bill or lower growth pushes it later.
Does the calculator include stamp duty and first home buyer concessions?
Yes. It applies each state's 2026-27 duty rates and first home concessions, including NSW First Home Buyer Assistance up to $1,000,000, Victoria's exemption up to $600,000 tapering out at $750,000, Queensland's first home concession to $800,000 and the full concession for new homes, and Tasmania's established home exemption which ended on 30 June 2026.
Is the first home owner grant included?
Yes, as an upfront amount when you choose a new home under your state's cap, for example $30,000 in Queensland for new homes and $20,000 in Tasmania after the 2026 reduction.
How is capital gains tax on the renter's portfolio handled?
Gains up to 30 June 2027 keep the 50% discount. Later gains use the new rules: a CPI-indexed cost base and a 30% minimum effective tax rate. Your share of the home you live in stays exempt as your main residence.
Is rent-vesting modeled?
Yes. The third path buys an investment property while you keep renting, with rental income, management fees, negative gearing, and the post-12 May 2026 limits that carry forward restricted deductions.
Do I need an account?
No. The calculator runs in your browser, nothing is uploaded, and there is no signup.
Cite this tool
BoringToolsKit. “Rent vs Buy Calculator Australia.” boringtoolskit.com/rent-vs-buy-calculator-australia/ (reviewed September 2026). Free to reference in articles, syllabi, and answer posts with a link.
Privacy: Inputs and results stay in this browser. Any future sponsored recommendation or advertisement will be clearly labeled and kept separate from the calculation.